83% of people say they trust recommendations from friends and family. In Nielsen's global survey of more than 30,000 online consumers, that put word of mouth at the top of 19 ad formats.1
For banks and credit unions, that trust has a dollar value.
A study of about 10,000 customers at a German bank found referred customers were worth at least 16% more than non-referred customers with similar demographics who joined at the same time.2 The bank paid 25 euros per referral. The researchers put the return on that reward at about 60% over six years.3
Referred customers were worth at least 16% more than comparable customers who came in another way.
So the question is rarely whether referrals work. It's how to design the offer and how to run it.
Key takeaways
- Referred customers can be measurably more valuable than customers acquired through other channels.
- 46 of 50 live programs require a new checking account, and 42 of 50 require a direct deposit or debit card use.
- 40 of 50 give the friend 60 or 90 days to qualify.
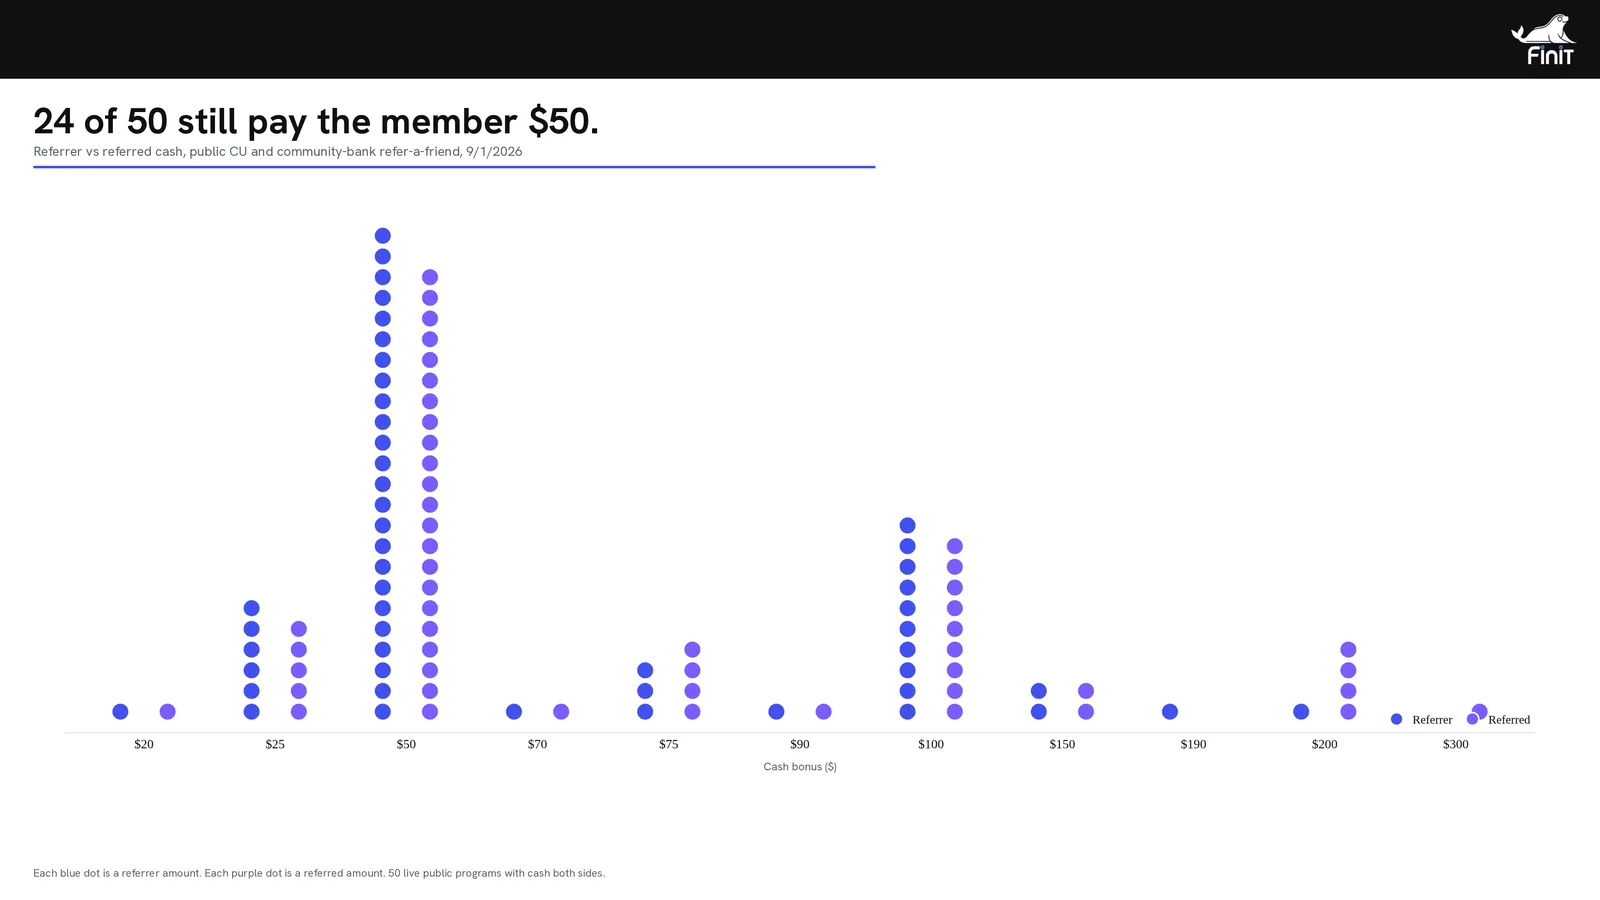
- $50 to each side is still the most common reward, at 21 of 50 programs.
- 27 of 50 cap what one referrer can earn in a year. $500 is the most common cap.
- The invite belongs where customers already bank: in the app.
What live programs require: the most common qualifications, ranked
We reviewed 50 public refer-a-friend programs that pay cash to both sides. 41 are credit unions. 9 are banks.4
Here's what a new account usually has to do before anyone gets paid, ranked by how many of the 50 programs ask for it.
- Open a new checking account: 46 of 50. That's 37 of 41 credit unions and all 9 banks.
- Make a direct deposit or use the debit card: 42 of 50. 34 of 41 credit unions and 8 of 9 banks ask for one or both.
- Qualify within 60 or 90 days: 40 of 50. 31 credit unions and all 9 banks set a 60-day or 90-day window for at least one step. 26 use 60 days somewhere in their terms and 18 use 90.
- Direct deposit: 30 of 50. 23 credit unions and 7 banks list one. Of the 24 that state a dollar amount, 19 set it between $200 and $500.
- Debit card purchases: 29 of 50. 24 credit unions and 5 banks list them. Ten purchases is the most common count: 13 of the 28 programs that name a number ask for 10.
- An annual cap on the referrer: 27 of 50. 19 credit unions and 8 banks limit how much one referrer can earn. $500 a year is the most common cap, at 17 programs.
- Keep the account open: 10 of 50. 6 credit unions and 4 banks require the account to stay open or in good standing for a set time, from about a month to a year. 3 take the reward back if it closes early.
- Enroll in eStatements: 10 of 50. 9 credit unions and 1 bank.
- Meet an opening deposit minimum: 9 of 50. 5 credit unions and 4 banks state one, from $1 to $50.
- Be new to the institution: 6 of 50. These programs spell out that the friend can't already have an account. 3 use a lookback of 12 to 18 months.
- Enroll in online or mobile banking: 4 of 50. All 4 are credit unions.
Only 4 programs require a direct deposit and debit purchases together with no either-or. Most let the friend pick one path.
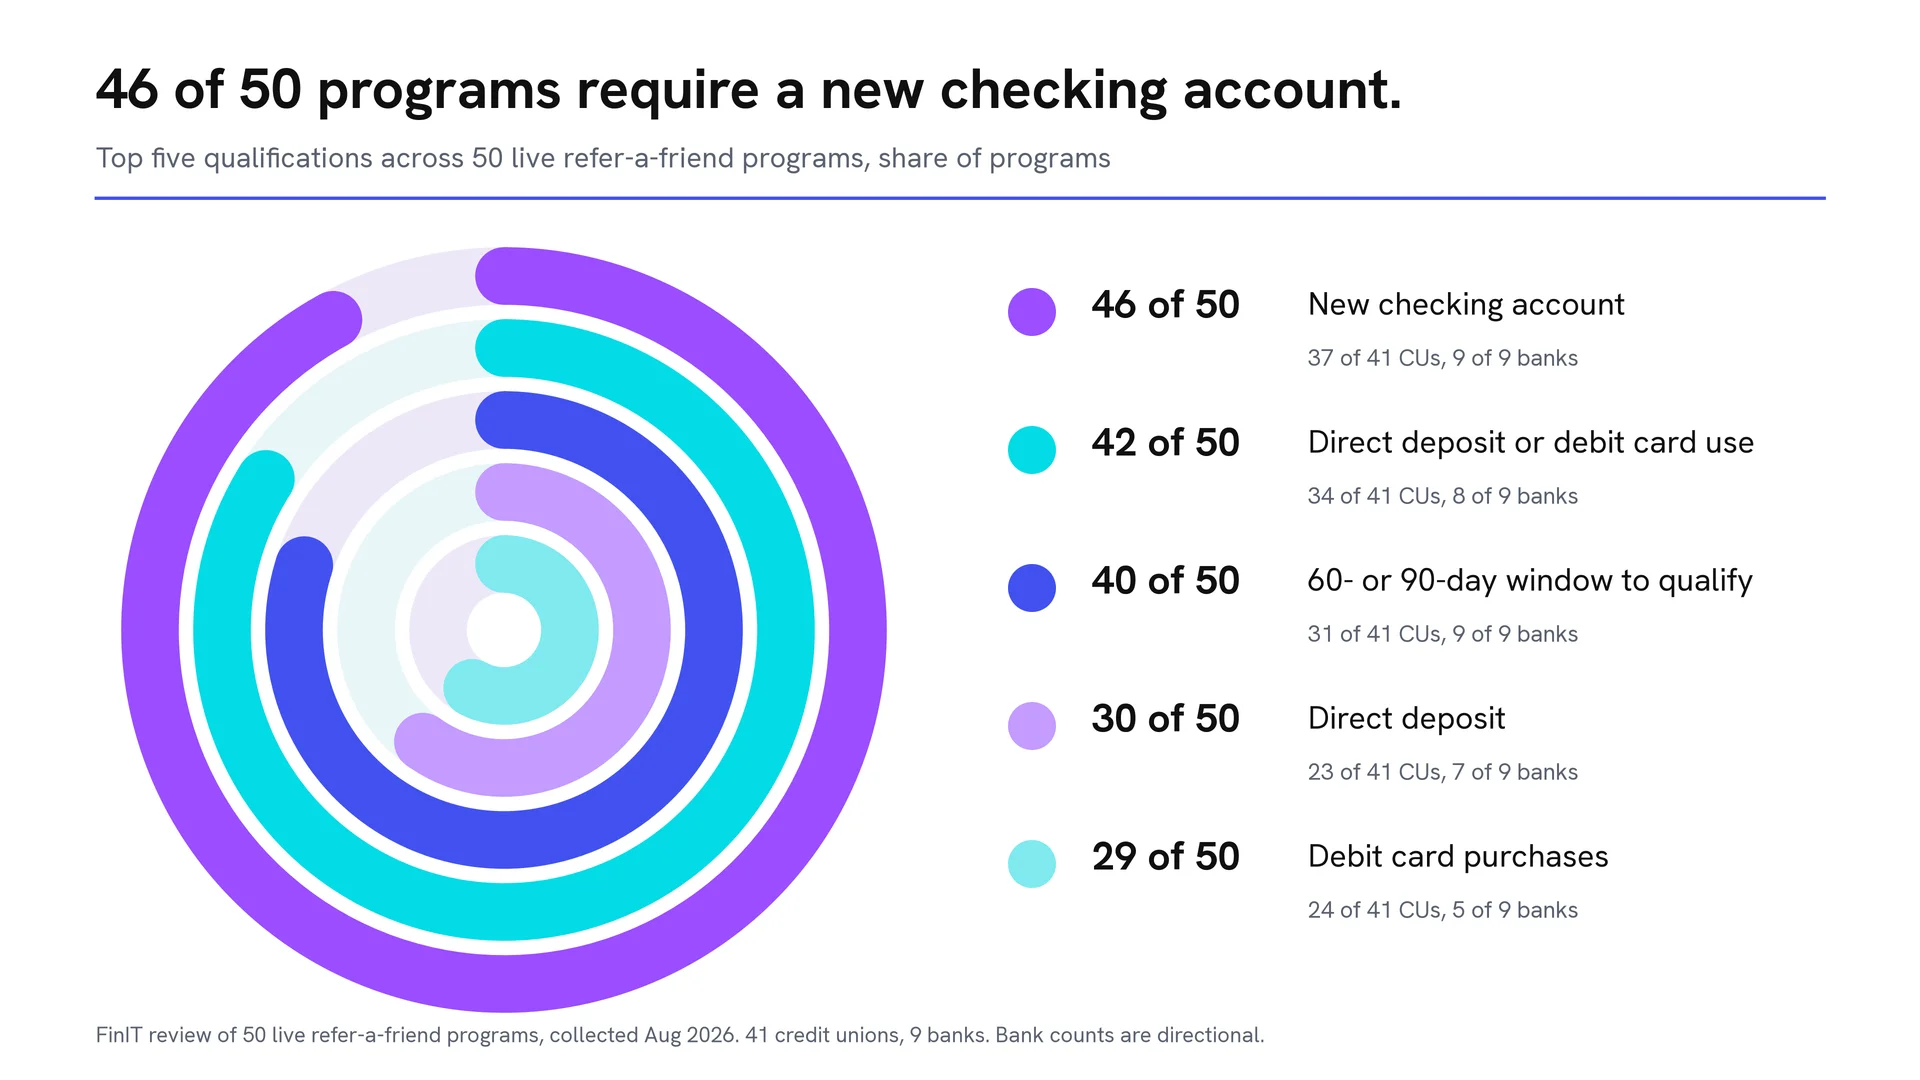
46 of 50 require a new checking account. 42 of 50 require a direct deposit or debit card use.
What they pay, ranked
- $50 to each side: 21 of 50. 24 of 50 pay the referrer $50 and 22 pay the friend $50.
- $100 to each side: 8 of 50. 10 pay the referrer $100.
- $25 to each side: 5 of 50.
- $75 to each side: 3 of 50.
42 of 50 pay the same amount to each side. The rest tilt toward the friend, up to $300.4
Credit unions and banks look alike here. Both groups center on $50, a new checking account and a 60-day or 90-day window. With only 9 banks in the set, read the bank counts as directional.
Designing the program
Set the goal first
Decide what a good new account looks like at your institution. Then write the qualification around it.
If you want primary accounts, require a recurring direct deposit. If you want card activity, require purchases. If you want paper out of the mail, add eStatements.
Every rule should be something your core or digital banking data can confirm. If someone has to read a form to check it, rewrite the rule.
Size the reward against what a new account is worth
The reward is only part of the cost. Staff time spent checking deposits and keying payouts counts too.
To size rewards against what a new account is worth, try our bank referral ROI calculator.
Disclose it correctly
A referral bonus on a deposit account is an advertised bonus. Banks follow Regulation DD (12 CFR 1030). Credit unions follow NCUA Part 707. Two of the 50 programs we reviewed also note that rewards are reported on a 1099-MISC. Confirm the treatment with your compliance and tax teams.
Running the program
Put the invite in the app
54% of U.S. bank customers say a mobile app is the way they manage their accounts most often. 9% say a branch.5
Yet 22 of the 50 programs we reviewed still run at least partly on printed forms, branch cards or off-channel web forms.4 An invite inside digital banking reaches every customer who logs in.
Track every referral automatically
Each invite needs a unique link or code. Each new account needs to be matched to its referrer. Then the system needs to watch for the deposit, the swipes and the deadline.
Doing that by hand works for a handful of referrals. It breaks once volume shows up.
Pay both sides by ACH
Most programs pay cash into both accounts. Paying by ACH, as soon as the friend qualifies, removes manual credits and gift card logistics.
Measure what matters
Track invites sent, accounts opened, accounts that qualified and cost per qualified account. Compare that cost with your other acquisition channels.
Where FinIT Refer fits
FinIT Refer runs the program inside digital banking. Customers and members refer from the app they already use.
FinIT tracks new accounts, direct deposits, debit swipes and eStatement enrollment against your rules. Rewards pay by ACH. Your team sees everything on a live dashboard.
It's white-label, plugs into Q2 and comes with US-based support. 20+ credit unions and banks work with FinIT.
Frequently asked questions
What are the most common requirements for a new checking account referral bonus?
In our review of 50 live programs, the most common requirements were a new checking account (46 of 50), plus a direct deposit or debit card activity (42 of 50), completed within 60 or 90 days (40 of 50). An annual referrer cap (27 of 50) is next, then keeping the account open and eStatements (10 of 50 each).
How much do banks and credit unions pay for a referral?
$50 to each side is the most common reward. Payouts in our review ranged from $20 to $200 for the referrer and $20 to $300 for the friend.
Do referral programs work for banks?
Research on a German bank found referred customers were worth at least 16% more than comparable non-referred customers.2
How are referrals tracked?
Usually with a unique referral link or code for each customer. The new account is matched to the referrer, then checked against the qualification rules.
Can customers refer more than one person?
Yes. Many programs cap the referrer's annual rewards. 27 of the 50 programs we reviewed set an annual cap, and $500 a year is the most common, at 17.
Sources
- Nielsen, Global Trust in Advertising, 2015. More than 30,000 online respondents in 60 countries.
- Schmitt, Skiera and Van den Bulte, "Referral Programs and Customer Value," Journal of Marketing, January 2011.
- Knowledge at Wharton, "Turning Social Capital into Economic Capital".
- FinIT review of 50 public credit union and bank refer-a-friend programs paying cash to both sides, collected August 2026. See Today's refer-a-friend reality.
- American Bankers Association and Morning Consult, November 18, 2025. Survey of 4,403 U.S. adults, October 1 to 6, 2025.